Official reasons (commercial / practical)
Google announced in 2011 it would invest ~US$300 million in a facility on a 2.7-hectare site in the Tseung Kwan O Industrial Estate (granted by Hong Kong Science and Technology Parks). It held a groundbreaking ceremony but never built anything. In December 2013 it surrendered the land.
Google’s stated reason was the lack of available land for expansion and the need to focus on sites that allowed economies of scale. It said it saw opportunity in Hong Kong but needed larger sites to keep up with rapid growth in users and traffic across Asia. It redirected investment to bigger facilities in Taiwan (Changhua) and Singapore instead. Hong Kong’s high land costs and scarcity of large contiguous plots were the core commercial constraints cited.
Political / geopolitical speculation
Google declined to comment on whether its difficult relationship with mainland China played a role (it had redirected Google.cn traffic to its uncensored Hong Kong servers in 2010 after disputes over censorship and cyber attacks). Some contemporary reports and later commentary (including a 2020 Hong Kong Free Press piece) suggested possible concerns about data security, proximity to China, or landlord/government access rights to data spaces. No official confirmation of political motives was ever given by Google; the company insisted the decision was purely commercial and that it was not scaling back other Hong Kong operations.
Nowadays — any “olive branch” (橄欖枝) to foreigners?
Hong Kong actively courts foreign (and mainland) data-centre and AI investment and markets itself as an international data hub / gateway.
Key recent signals include:
- Government facilitation: a dedicated Data Centre Facilitation Unit provides one-stop support for overseas firms on land, power, connectivity, and compliance. Official materials highlight free flow of information, common-law protections, IP security, reliable power, and zero customs duties on equipment.
- New land and capacity: large sites are being tendered (e.g., the ~11-hectare Sandy Ridge / Sha Ling data-facility cluster in the Northern Metropolis, awarded in early 2026 with multi-billion-HK$ investment commitments aimed at massively expanding computing power). Tseung Kwan O remains a core cluster.
- Multinational expansion continues: Equinix opened its sixth Hong Kong facility (HK6) in mid-2026 — an AI-ready, liquid-cooled centre representing its largest investment in the city in a decade, with direct links into the Greater Bay Area. Other international operators (Digital Realty, Global Switch, Goodman, etc.) and cloud providers maintain or grow presence. AWS and others also have capacity in the market.
- Policy positioning: Hong Kong promotes itself as a neutral platform for cross-border data flows, AI compute, and as a springboard for both international firms entering Greater China and mainland firms going global. InvestHK tracks and assists overseas company set-ups.
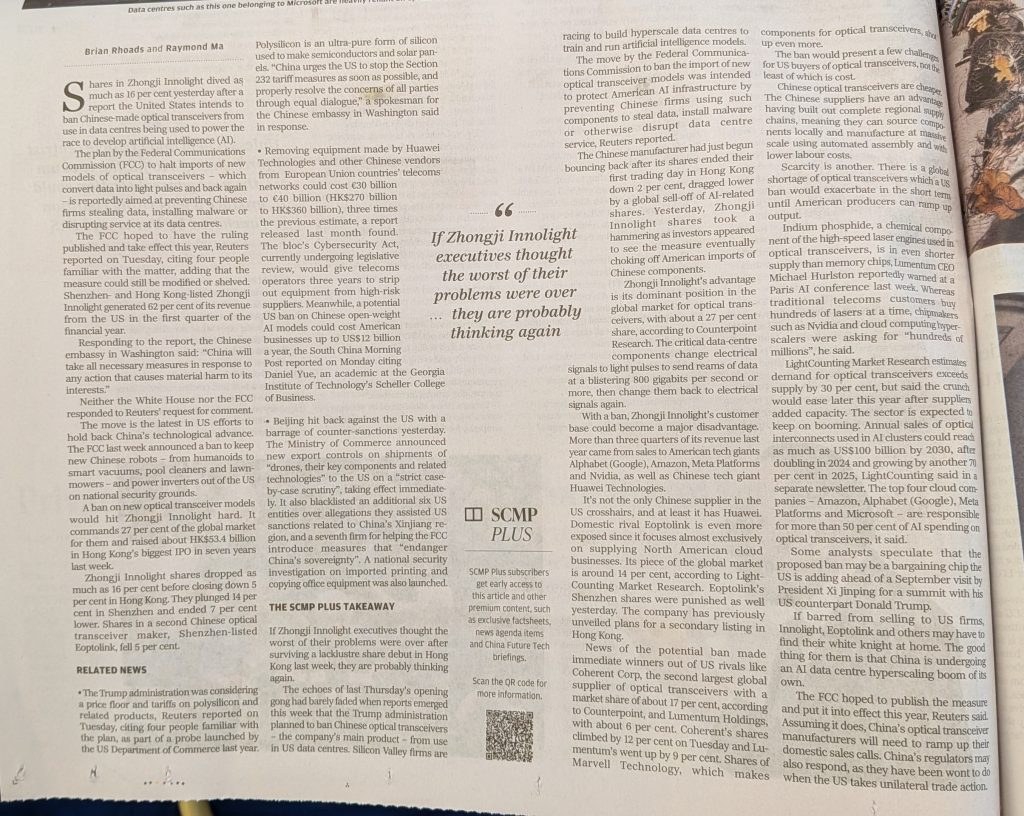
Despite geopolitical tensions and the post-2020 national-security environment, the practical “olive branch” is visible in land supply, infrastructure investment, facilitation services, and continued foreign operator activity. The market has shifted heavily toward AI/high-density workloads, with both foreign colocation providers and mainland hyperscale/compute players expanding.
However, none of foreigner investors to build up new Data centers, but many mainland investors M&A existing DCs in HongKong.